Roof insurance questions in Arkansas
A roof inspection establishes the physical concern. An insurance policy establishes whether a loss is covered and how payment is calculated. Keep those two decisions connected without treating them as the same answer.
Understand the insurance terms around roof work
Insurance paperwork can make a roof project feel like one large decision, but the roof scope and claim payment follow different rules. The roofer assesses the material and repairs; the insurer decides coverage under the policy.
This guide explains deductibles, depreciation and replacement-cost payment using Arkansas Insurance Department and NAIC sources. It also explains why an initial check can be different from the full cost of the work.
Damage assessment and insurance coverage
- The physical roof finding
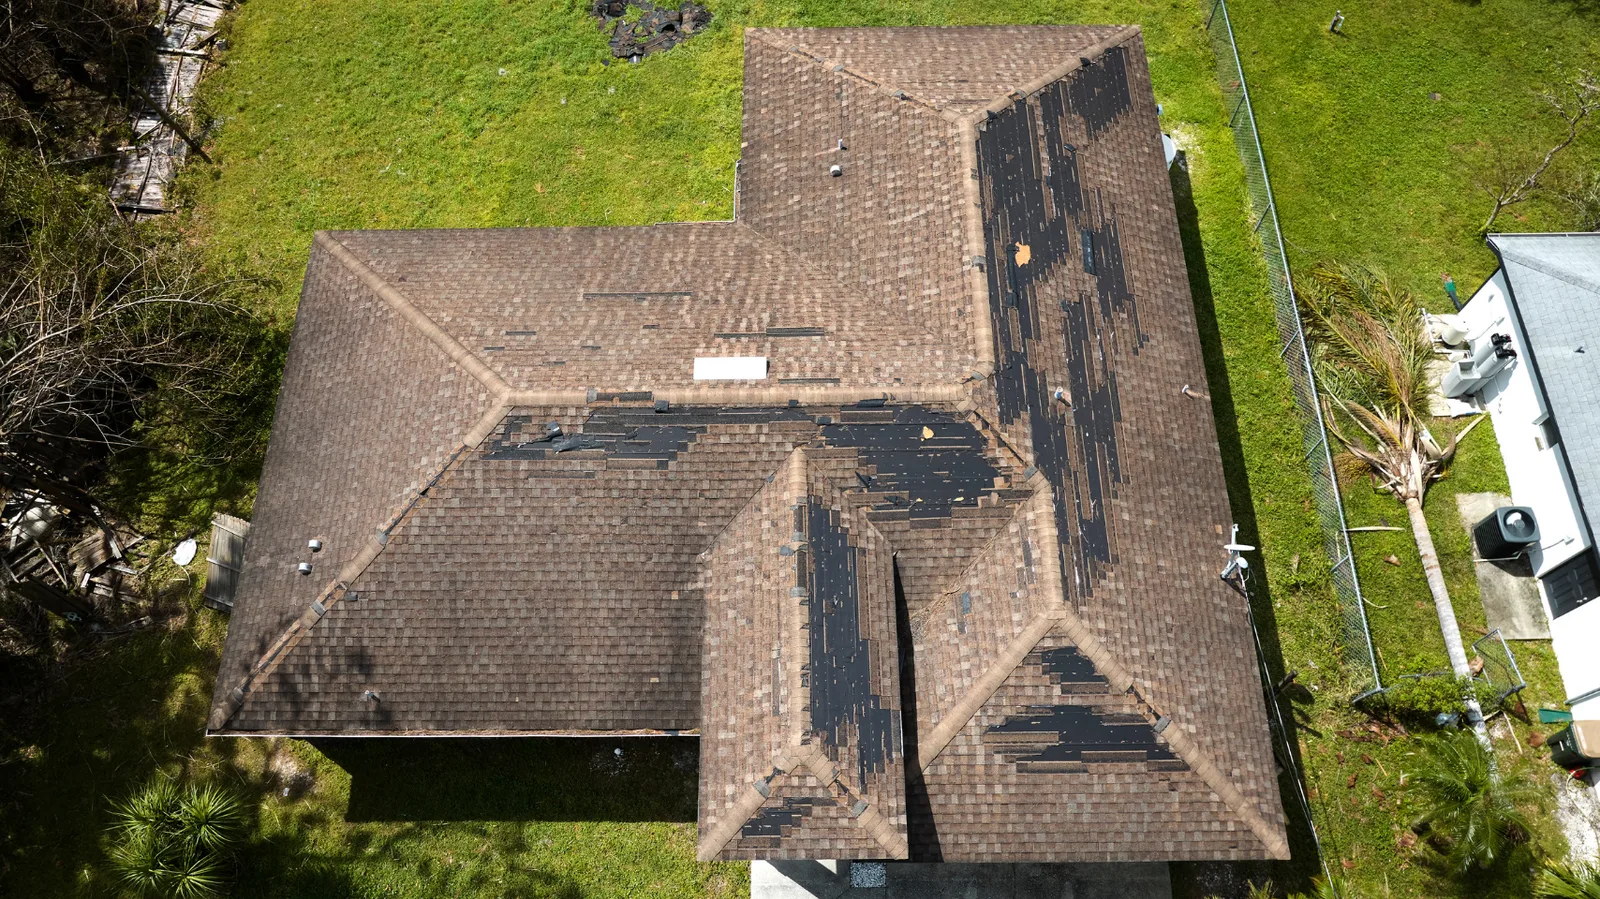
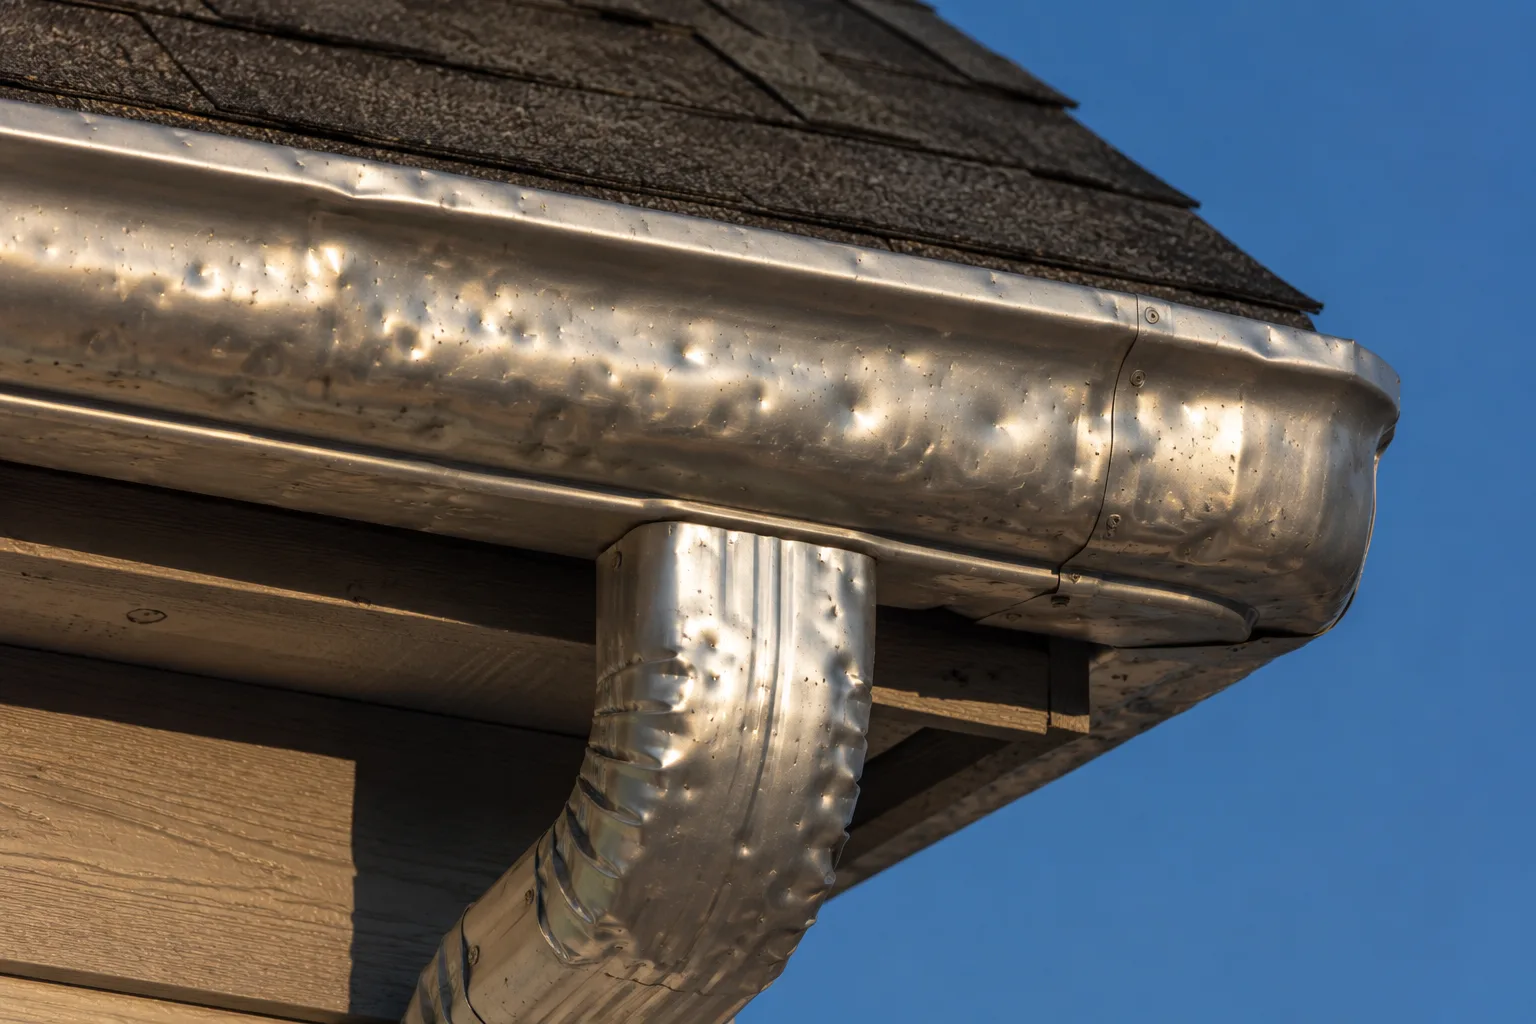
An inspection can identify damaged material, a failed detail and the work needed to restore it. The condition of adjoining roofing and concealed layers can change that scope. A weather report adds context but cannot prove damage at an address.
- The insurer’s coverage decision
The insurer applies the policy, endorsements, exclusions and cause of loss. Sudden covered damage and ordinary wear are different questions. A roofing estimate does not guarantee acceptance of a claim or a particular settlement.
- The terms for this roof
A dwelling policy can have roof-specific payment limits or an actual-cash-value endorsement even where other parts of the home have replacement-cost coverage. The declarations, endorsements and claim explanation establish the applicable terms.
Deductible, depreciation and replacement-cost payment
The Arkansas Insurance Department rescinded the older blanket prohibition on labor depreciation in its August 1, 2017 bulletin. Read Bulletin 10-2017.
For the basic payment distinction, see the NAIC’s January 2025 explanation of ACV and replacement cost.
Keep urgent protection and claim records in view
If a roof is leaking, address the immediate protection need and notify the insurer promptly. Temporary measures to limit additional damage are different from committing to the permanent repair scope.
- Keep available records
Safe photos, the date you noticed the problem and receipts for necessary temporary work can help document the loss. There is no reason to climb onto a damaged roof to gather them.
- Coordinate the permanent work
Arkansas Insurance Department guidance calls for insurer inspection and agreement on appropriate repair cost before permanent repairs. The actual policy sets reporting, completion and payment conditions; missed deadlines can affect recovery.
Repair or replace under the actual roof scope
- Repairability and covered scope
The roof may need a focused repair or wider work depending on damage and remaining material. Coverage for that scope still depends on the loss and policy. Existing wear does not become storm damage because a storm occurred nearby.
- Material matching
Availability, profile and color weathering can affect repair. Whether a policy pays for additional matching work is a separate coverage question; there is no automatic whole-roof entitlement from a color difference alone.
- An unclear claim decision
The insurer’s written explanation should connect its decision to the policy terms. Arkansas Insurance Department Consumer Services provides an official complaint path when a policyholder needs help with an unresolved insurance issue.
Roof insurance questions in Arkansas FAQs
Does insurance cover an old roof?
Age alone does not answer coverage. The cause of loss, exclusions, roof endorsements and payment terms matter. Wear and deterioration are different from a covered sudden event, and age can also affect depreciation.
Why is the first check lower than the replacement price?
The first payment may subtract the deductible and depreciation, or the roof may have actual-cash-value coverage. Recoverable depreciation depends on replacement-cost terms, completed work, documentation and deadlines in the policy.
Should a leaking roof wait for the claim decision?
Active water entry needs attention while the insurer considers the claim. Keep people safe, discuss temporary protection and notify the insurer promptly. Coordinate permanent repairs with the insurer’s inspection and the actual scope.
Start with the condition of your roof
Tell us the roofing concern and whether water is entering now. Riverport Roofing can begin with a free inspection of the physical roof.